VAIDS and the need for effective tax administration in Nigeria | Olajide Olutuyi

VAIDS and the need for effective tax administration in Nigeria | Olajide Olutuyi

As
part of efforts to improve non-oil revenue amid a global outlook of low oil
prices, Nigeria’s Acting President, Yemi Osinbajo, recently signed an Executive
Order (EO) on the Voluntary Asset and Income Declaration Scheme (VAIDS). The
main objective of the scheme – which commenced on July 1, 2017 and will last
for a period of nine months – is to help expand the country’s tax base.


Other
objectives of the scheme, as announced by the Minister of Finance, Kemi Adeosun,
include increasing tax-to-GDP ratio from 6% to 18% by 2020, and improving
compliance with existing tax laws. VAIDS is also expected to curb the use of
tax havens, discourage tax evasion, and tackle illicit financial flows. With
the introduction of VAIDS, the government hopes to encourage voluntary
disclosure of previously undisclosed assets and income and the payment of
outstanding tax liabilities.

In
one of its reports on Voluntary Disclosure Programmes, the Organization for
Economic Co-operation and Development (OECD) describes VDPs as “opportunities
offered by tax administrations to allow previously non-compliant taxpayers to
correct their tax affairs under specified terms. When drafted carefully,
voluntary disclosure programmes benefit everyone involved – taxpayers making
the disclosure, compliant taxpayers, and governments.” The Nigerian VAIDS is
being implemented by the Federal Inland Revenue Service (FIRS) in collaboration
with all 36 State Internal Revenue Services (IRS) and the FCT IRS.

While
signing the EO on the scheme, Osinbajo said it had become imperative for the
government to do something about the low level of tax compliance, adding that,
“When people pay taxes, they pay more attention to what government is doing.
There’s a greater level of political and social consciousness. Taxes are not
only about boosting government revenues. When people pay taxes, they hold the
government to account more.” He is right. In developed countries, citizens pay
their fair share of taxes and they have a say in the way their representatives
in government manage government funds.

Considering
Nigeria’s low tax-to-GDP ratio, and the fact that out of a taxable class of
about 69 million people, only 14 million are currently in the tax net, the
implementation of VAIDS could go a long way in increasing non-oil revenue.
Despite having a non-oil sector that accounts for up to 93% of Nigeria’s GDP,
government’s non-oil revenue in 2016 was N2.99 trillion (or 2.9% of GDP).
Suffice to say, though, that there was a decline in non-oil collection from the
N3.08 trillion recorded in 2015. Nevertheless, this does not alter the main
gist, which is the dismal performance of the non-oil sector in terms of
generating revenue for the government.

Permanent
and temporary disclosure schemes
Voluntary
disclosures regarding tax matters are not new in tax administration. Indeed,
VDPs are widely used in developed countries, helping to enhance the
effectiveness of their tax administration. Voluntary disclosure programmes can
generally be grouped into two categories, namely permanent or temporary
programmes. The Nigerian VAIDS is considered a temporary programme.

The
Canadian Voluntary Disclosures Program is a permanent programme. It gives
individuals and companies a second chance to change a tax return that was
previously filed or to file a return that should have been filed. To be
eligible, it must be voluntary. Should an individual or company be contacted by
the Canada Revenue Agency before making the disclosure, it won’t be considered
voluntary.

South
Africa also operates a permanent VDP as part of its tax administration.
However, a temporary VDP was introduced last year. Called the Special Voluntary
Disclosure Programme (SVDP), it is similar to Nigeria’s VAIDS. The SVDP window
period is between October 1, 2016 and August 31, 2017. It is meant for
individuals and companies who have not, in the past, disclosed tax and exchange
control defaults in relation to offshore assets.

In
developed countries, there are benefits associated with voluntary disclosure,
including reduced penalties and an allowance to negotiate for protection
against criminal prosecution – in serious cases of default.

In
the case of VAIDS, some benefits to individuals and companies were also listed
during the rollout, such as: immunity from prosecution for tax offences;
immunity from tax audit; waiver of interest; and waiver of penalties. However,
for there to be institutionalization of voluntary disclosure in Nigeria’s tax
administration, there needs to be an enactment of a permanent VDP law by the
National Assembly. The South African Revenue Service Voluntary Disclosure
Programme (VDP), which came into effect on October 1, 2012, is administered
under the Tax Administration Act, 2011.
VDPs
have been found to rake in significant funds for governments. Canada’s VDP
raked in $1.3 billion in the 2014-2015 fiscal year, out of which about $780
million came from offshore disclosures. Similarly, the United States Offshore
Voluntary Disclosure Program (OVDP) has raked in about $10 billion in taxes,
interest and penalties since 2009. In Nigeria’s case, the VAIDS has a tax
revenue target of $1 billion.

Revamping
tax administration
For
VAIDS or a future VDP law to be very successful, an efficient and effective tax
administration has to be in place. The country’s current tax administration is
bogged down with several issues, ranging from lack of accurate data, duplicity
of taxes and crude collection systems. These issues will need to be dealt with.

In
his book, The Wealth of Nations, published in 1776, Scottish economist, Adam
Smith, outlined the four principles or canons of a tax system: 1) “The subjects
of every state ought to contribute towards the support of the government, as
nearly as possible, in proportion to their respective abilities; that is, in
proportion to the revenue which they respectively enjoy under the protection of
the state.” 2) “The tax which each individual is bound to pay ought to be
certain, and not arbitrary. The time of payment, the manner of payment, the
quantity to be paid, ought all to be clear and plain to the contributor, and to
every other person.” 3) “Every tax ought to be levied at the time, or in the
manner, in which it is most likely to be convenient for the contributor to pay
it.” 4) “Every tax ought to be so contrived as both to take out and to keep out
of the pockets of the people as little as possible over and above what it
brings into the public treasury of the state.”

Modern-day
economists have re-stated the above four canons as: equality (everybody ought
to pay the same rate or percentage of his income as tax); certainty (there
should be no ambiguity about the time, manner and quantity of payment);
convenience (the sum, time and manner of payment of taxes should not be
burdensome to the taxpayer); and efficiency (taxes should be as simple as
possible and collection costs minimised). Much of these principles are lacking
in Nigeria’s tax administration.

The
FIRS and the Ministry of Finance would need to work hard to revamp the
country’s tax administration. Although Executive Chairman of the FIRS,
Babatunde Fowler, has expressed optimism that the agency and the government
will meet their revenue target for VAIDS, the tax agency will need to do more
than a temporary disclosure programme to boost tax revenue in the country. It
should also look at how a permanent VDP can be embedded in the tax
administration.

But
the much bigger task is putting in place policies to engender sustainable
inclusive economic growth, increase access to funding for small businesses and
revitalize the private sector. Tax revenue plays a key role in building the
economy. However, the economy has to be supported to grow and diversify. And
the economic diversification agenda of the government is hinged on boosting
non-oil revenue, of which tax revenue is a huge part of.  

While
VAIDS remains a temporary programme, the tax agency must also ensure punitive
measures for tax defaulters are clearly stated. Otherwise, VAIDS will soon join
the pool of several government programmes that were rolled out with pomp and
pageantry but never achieved their objectives.

In
designing an effective tax system, the FIRS and the Finance Ministry must bear
in mind the power of taxation, as James Madison, America’s fourth President
opined: “The power of taxing people and their property is essential to the very
existence of government.”
Senior Financial Analyst at Scouts Canada
@jideolutuyi
This article was first published here
Difference between Letter of Dismissal & Letter of Termination | Adedunmade Onibokun

Difference between Letter of Dismissal & Letter of Termination | Adedunmade Onibokun

It
is important to note that an employment relationship cannot be forced upon
either an unwilling employer or employee. Therefore, an employer has a right to
hire and fire, likewise an employee has the right to resign from an employment.

Many a times, the words “dismissal” and “termination”
are used interchangeably when referring to an employee whose employment has
seized.  This may be appropriate in general
discussions, however, under the law, a dismissal and a termination of
employment have completely different interpretations and consequences. A letter
of resignation represents an employee’s desire to quit a job; however, the
effects of a letter of dismissal from an employer are quite different from
those of a letter of termination.  
The Oxford Dictionary describes the word “dismiss”
to mean to send away from one’s presence or employment, it also describes it as
meaning to “reject”. Likewise, a letter of dismissal is a rejection of the
employee by the employer, such rejection which is usually for a reason.  
The first difference between a dismissal
and a termination is that a dismissal is usually punitive in nature while a
termination is simply bringing an employment contract to an end. This implies that
while an employer may well under the law terminate an employment, choosing to
rather dismiss an employee seeks to punish that employee for an act of
misconduct. This was illustrated in Eigbe V Nigeria Union Of Teachers
(2007)
LPELR-8310(CA)
where the court held that –
“It is now well settled that in statutory
employment, as well as in private employment, the employer can dismiss an
employee where the accusations against such employee is of gross misconduct
involving dishonesty bordering on criminality, and in such a case, it is not
necessary, nor is it required under Section 36 (1) of the 1999 Constitution
that employee must be tried in a court of law.”
Another difference between a dismissal and
a termination is that, under a termination, the employee is liable to receive a
gratuity and other terminal benefits, however, an employee who has been
dismissed may not be liable to receive any such benefits. This is further
stated in Union Bank Of Nigeria Plc v. Soares
(2012)
LPELR-8018(CA)
, where the court held that –
“There is a clear distinction between termination of a
contract of employment and a dismissal. Termination gives the parties the right
to determine the contract at any time by giving the prescribed period of
notice. Dismissal on the other hand, is a disciplinary measure which carries no
benefits.”
A third difference between a dismissal and
a termination is that, an employee whose contract of employment is terminated
without notice will be liable to collect a salary in lieu of notice, while this
is not the case under a dismissal. This was aptly put by the Supreme Court in Ekunola
V. Cbn & Anor.
(2013)
LPELR-20391(SC)
where the court deliberated whether an employee dismissed on the ground of allegation of gross
misconduct is entitled to notice or salary in lieu of notice, it was held that  –
 “Where his dismissal is founded on the
allegation of gross misconduct the appellant is not entitled to any notice or
salary in lieu of notice …………. And it would be wrong in law to make any awards
to him in these regards.”
The above is a guide to help when
considering, the legal implications of a letter of dismissal and a letter of
termination.
Adedunmade Onibokun
@adedunmade

Legal Contracts for Service and of Service in Employment Relationships |Micheal Dugeri

Legal Contracts for Service and of Service in Employment Relationships |Micheal Dugeri

Introduction
Contracts of
service and contracts for service both connote an employment relationship
between the parties. However, they differ in their nature and the legal
consequences.
  Understanding the
difference between both contracts is important for two main reasons, namely,
the nature of each party’s respective obligations, and which court has
jurisdiction in the event of dispute between the parties.

Delineation
A contract
of service is an agreement between an employer and an employee. In
a contract for service, an independent contractor, such as a self-employed
person or vendor, is engaged for a fee to carry out an assignment or project.
The line of
demarcation between an independent contractor and an employee is very thin and
the two concepts sometimes overlap. In such a situation, the question about the
relationship of employer and employee needs to be determined with reference to
the facts and circumstances of each case as to who are the parties to the
contract, who pays the wages, who has the power to dismiss, what is the nature
of the job, and the place of executing the job, all have to be kept in mind.
The Supreme Court, in Shena Security Co.
Ltd v. Afropak (Nig.) Ltd & 2 Others
[2008] 18 NWLR (Pt. 1118) 77 SC; [2008] 4 – 5 SC (Pt. II) 117
laid
down the following factors that should guide courts in determining which kind
of contract the parties entered into –
If
payments are made by way of
“wages” or “salaries” this is indicative that the contract is one
of service. If it is a contract for service, the independent contractor gets
his payment by way of
“fees”. In like manner, where payment
is by way of commission only or on the completion of the job, that indicates
that the contract is for service.
Where
the employer supplies the tools and other capital equipment there is a strong
likelihood that the contract is that of employment or of service. But where the
person engaged has to invest and provide capital for the work to progress that
indicates that it is a contract for service.
In a
contract of service/employment, it is inconsistent for an employer to delegate
his duties under the contract. Thus, where a contract allows a person to
delegate his duties there under, it becomes a contract for services.
Where
the hours of work are not fixed it is not a contract of employment/of service.
See Milway (Southern) Ltd v. Willshire
[1978] 1 RLR 322.
It is
not fatal to the existence of a contract of employment/of service that the work
is not carried out on the emjployer’s premises. However, a contract which
allows the work to be carried on outside the employer’s premises is more likely
to be a contract for service.
Where
an office accommodation and a secretary are provided by the employer, it is a
contract of service/of employment.
Dispute resolution in contracts of service
and for service
Jurisdiction is the all important factor
that the courts will consider in any case that is brought before them. It is
tempting to assume that all employment or work related disputes are to be
settled by the National Industrial Court (NIC) by virtue of the Constitution of
the Federal Republic of Nigeria (Third Alteration) Act 2010. However, this is
not always the case.
Section 254 C (i) (a) of the Act provides
that “the National Industrial Court shall
have and exercise jurisdiction to the exclusion of any other court in civil
causes and matters (a) relating to or connected with any labour, employment,
trade unions, industrial relations and matters arising from workplace, the
conditions of service, including health, safety, welfare of labour, employee,
worker and matters incidental thereto or connected therewith
”.
The above provision notwithstanding, the NIC
has held in many cases that its jurisdiction covers only disputes relating to contracts
of service, and not contracts for service. This means that only strictly
employment contracts may be litigated before the NIC. Cases of an independent
contractor, such as a self-employed person or vendor, engaged for a fee to carry
out an assignment or project, are not justiciable before the NIC. Such cases
may therefore be more appropriately brought before the regular courts (i.e High
courts or magistrates courts, depending on the circumstances). In other words,
breach of contract for service is regarded as any other breach of contract and
treated as such.
In a recent case of The Registered
Trustees of Three Wheeler Beneficiaries Operators Association, Lagos State v.
Road Transport Employers Association of Nigeria
(unreported Suit No.
NICN/LA/407/2013), the ruling of which was delivered on 10th May 2017, the NIC held
thus:
“This
Court does not have jurisdiction over every workplace issue. For instance, as
against contracts of service,
this Court does not assume jurisdiction over contracts for service, and yet contracts for service are workplace issues
strictly so called. See Mr. Henry Adoh
v. EMC Communications Infrastructure Limited [2015] 55 NLLR (Pt. 189)
546 NIC, Ozafe Nigeria Limited v.
Access Bank of Nigeria Plc unreported Suit No. NICN/LA/179/2014 the
ruling of which was delivered on 16th March 2016 and Engr. Jude Ononiwu (Trading under the name of Judeson Chemical and
Engineering Co. Ltd) v. National Directorate of Employment & Another
unreported Appeal No. CA/OW/32/2015 the ruling of which was delivered on 22nd
May 2015”.
In the case of Lawrence Igwegbe v. Standard Alliance
Life Assurance Limited
(unreported Suit No. NICN/LA/465/2013),
the judgment of which was delivered on 11 July 2017, the NIC had to determine on
the facts before it, if the relationship between the Claimant and the Defendant
was one of an employment relationship (contract of service) or one in
which the claimant was an independent contractor (contract for service).
The court held that the fact that the Claimant was on commission and not on
salary was very suggestive that the relationship was one of a contract for
service. The court relied on the Supreme Court decision in Shena Security Co. Ltd and held
that salary is a component part of the employment relationship strictly
speaking (contract of service).
The facts of the case are that the Claimant
was employed as Agency Manager by the Defendant, who is an insurance company.
While the Claimant argued before the court that his relationship with the
Defendant was an employment relationship, his evidence before the court showed
that he was on commission and not on a salary. This meant that he was an
independent contractor to the Defendant, and not necessarily its staff. The
court in this case took judicial notice of the fact that insurance agents are
in the main not salaried employees, but are paid commission based on the volume
of insurance business they bring in. The court declined jurisdiction, since it
was a case of contract for service as against contract of service.  
In the case of Engr.
Jude Ononiwu (Trading under the name of Judeson Chemical and Engineering Co.
Ltd) v. National Directorate of Employment & Another
,
the claimant had
entered into a contract as a trainer with the 1st defendant under the 1st
defendant’s National Open Apprenticeship Scheme of Skill Acquisition Programme.
As a result, the 1st defendant sent trainees to the claimant for training.
Between 1996 and 2000, the claimant trained for the 1st defendant a total
number of 2204 trainees at the training cost of N6,000.00 per trainee bringing
the total debt owed the claimant to N13,776,000.00 only. When the 1st defendant
refused to pay this sum after repeated demands, the claimant accordingly sued
for it at the Federal High Court. The Federal High Court transferred the matter
to the Owerri Division of the NIC on the ground that the issue is a labour
issue in respect of which it had no jurisdiction given the provision of section
254C(1) of the 1999 Constitution, as amended.
The NIC, not certain as to whether it had
jurisdiction either, decided to refer the case to the Court of Appeal to
determine if the NIC has jurisdiction over contracts for service. In
determining this issue, the Court of Appeal held that the court with
jurisdiction, considering the facts of the case, was the State High Court, and
not the Federal High Court nor the NIC. The Court of Appeal based its decision
on the fact that the case arose from a simple contract between the claimant and
the 1st defendant/respondent; and that the relationship between the parties was
contractual, the contract being one of contract for service as opposed to a
contract of service. The Court of Appeal then considered section 254C (1) in
terms of the jurisdiction of the NIC, section 251(1) in terms of the
jurisdiction of the Federal High Court and section 272(1), (2) and (3) in terms
of the jurisdiction of the State High Court, and then concluded that the claims
of the claimant in the case do not relate to the sections dealing with the
jurisdiction of the NIC and the Federal High Court. Relying on
Onuorah v. Kaduna refining and Petrochemical Co. Ltd [2005] LPELR 2707 (SC)
and Integrated Timber & Plywood Products Ltd v. Union Bank of Nig. Plc
[2006] 5 SCNJ 289, the Court of Appeal held that neither the NIC nor the
Federal High Court had jurisdiction over the matter.
Employer tax obligations in contracts of
service and contracts for service
Employees under contract of service are deemed to
have employment contract with the organisation that they work for, which
entitle them to employment benefits such as wages and salary, pension, medical
insurance and other similar employment benefits. In a contract for service,
however, an independent, self-employed, individual is contracted to provide a
specific service for the organisation in return for a fee. There is no
employer-employee relationship between the organisation and the employees of
the independent contractor.
Section 81 of the Personal Income Tax Act Cap P8,
LFN 2004, as amended to date (PITA) provides that for employees – under a
contract of service, it is the responsibility of their employers to deduct and
remit income taxes from the emoluments paid to such employees. Section 82 of
PITA provides further that the employer is answerable to the tax authorities
for taxes deducted from the employees. The employer is required to file annual
returns in respect of emoluments paid to their employees and account for the
taxes withheld and remitted to the relevant tax authorities.
Section 81(2) of PITA requires the employer to file
annual returns not later than 31 January of every year in respect of all
emoluments paid to its employees in the preceding year. Failure to comply
attracts a penalty, upon conviction. Whenever the tax authorities intend to
conduct tax audit enquiries in respect of employees’ personal income taxes, the
employer is usually held answerable.
In cases of contracts for service, however, the
independent contractor or self-employed individual is personally responsible
for his own taxes. Such individuals are expected to file personal income tax
returns under the self-assessment regime. However, the company to whom the
services are rendered has the responsibility for deducting and remitting
withholding taxes on the fees payable under the contract at applicable rate. In
the same vein, a self-employed individual has an obligation to register for
value added tax (VAT) and charge VAT on invoices issued for services rendered,
unless such service is specifically exempt from VAT.
The Value Added Tax Act Cap V1 LFN 2004 as amended
(VATA) defines a taxable person as an individual or body of individuals,
family, corporations sole, trustee or executor or a person who carries out in a
place an economic activity, a person exploiting tangible or intangible property
for the purpose of obtaining income therefrom by way of trade or business or a
person or agency of government acting in that capacity. For the purpose of
VATA, an individuals under a contract for service falls under this category.
In addition to the need to account for tax, the Pension
Reform Act, 2104 mandates employers with five or more employees to make
contributions on behalf of their employees into an approved pension fund. As
explained earlier, individuals with contracts of service are employees. Hence,
pension contributions are mandated for them but not for individuals with a
contract for service. Individual with a contract for service could make
voluntary pension contributions into their Retirement Savings Account (RSA) if
they so desire.
Conclusion
In the world of work, it is not always easy
to distinguish a contract of service from a contract for service. Sometimes,
the nature of the relationship between the parties is deliberately made nebulous
in order to hide its true identity (and thereby deny one party of certain
rights). The
International Labour Organisation (ILO), well aware of
this fact, has provided guidance on how Courts should approach the issue, if it
arises. In the ILO Report titled, The Scope of the Employment Relationship
(ILO Office: Geneva), 2003 at pages 23 – 25, it is stated thus:
The
determination of the existence of an employment relationship should be guided
by the facts of what was actually agreed and performed by the parties, and not
by the name they have given the contract. That is why the existence of an
employment relationship depends on certain objective conditions being met (the
form in which the worker and the employer have established their respective
positions, rights and obligations, and the actual services to be provided), and
not on how either or both of the parties, describe the relationship. This is
known in law as the principle of the primacy of facts, which is explicitly
enshrined in some national systems. This principle might also be applied by
judges in the absence of an express rule.
The ILO concluded by advising that the
Judge in a labour dispute must normally decide on the basis of the facts,
irrespective of how the parties construe or describe a given contractual
relationship.

Micheal Dugeri

Corporate Commercial Lawyer at Austen-Peters & Co.

Senate Conducts Overight Of The Lagos – Ibadan Segment Of The Lagos To Kano Railway Modernisation Project

Senate Conducts Overight Of The Lagos – Ibadan Segment Of The Lagos To Kano Railway Modernisation Project

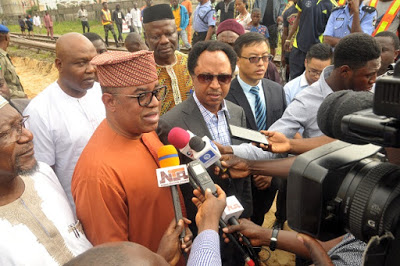
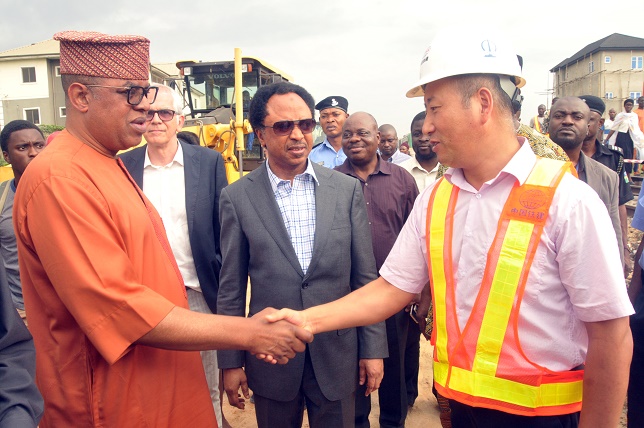
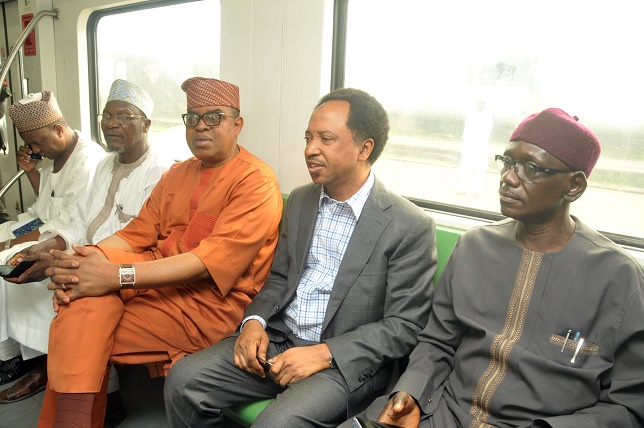
The Joint Senate Committee on Local and
Foreign Debt and Land Transport on Monday, 7th August, 2017
conducted an oversight visit to the Nigerian Railway Corporation Headquarters
and the Project Office of the China Civil Engineering Construction
Corporation CCECC in Ebute Metta, Lagos. The purpose of the visit was to assist
the committee assess the project implementation plan for the recently approved
loan request by the Federal Government from the China Exim Bank for the purpose
of completing various railway rehabilitation/construction projects across the country.

Chairman of the Senate Committee on Land
Transport Senator, Gbenga B Ashafa, and Chairman, Senate Committee on Local and
Foreign Debts, Senator Shehu Sanni, led the delegation from the Senate. Other
members of the Joint Committee who were present include Senator Yahaya Abdulai
and Senator Philip A. Gyunka. The Permanent Secretary of the
Ministry of Transport, Alhaji Sabiu Zakari, Managing Director of the Nigerian
Railway Corporation, Mr. Fidet Okhiria and the representative of the Managing
Director of CCECC, Mr. Leo Yinv received the Senators.

In his speech, Ashafa stated, “The focus of
this visit is to immediately set in perspective our commitment to ensuring a
high level of accountability in public expenditure. This is in line with our
constitutional responsibility to carry out periodic oversight functions to the
Ministries, Departments and Agencies under the supervision of the Joint
Committee.”

Speaking further, the Senator called on the
project contractor CCECC to ensure that they maximize the local materials and
manpower in order to have direct impact on the Nigerian Economy. In his words,
“We are confident that the Lagos to Kano, and Calabar to Lagos
railway modernization projects would in no small way further reinvigorate
the Nigerian economy through the creation jobs. We therefore call on CCECC to
maximize local content in the in the area of raw materials and labour force.”
In Similar Vein, the Chairman of the Senate
Committee on Local and Foreign debt, Senator Shehu Sanni stated that with the
recent approval of the Railway Loan by the Senate, the Contractor has no excuse
but to deliver on  its mandate.

On his part, the representative of the
contractor, Mr. Leo Yinv took the members of the committee through the Project
Implementation Plan for the completion of the Lagos to Ibadan Segment of the
Lagos to Kano Railway modernization project and assured that while all
pre-fabrication works was being done in the interim, substantial earthwork
would commence on the project towards the end of November 2017.

From the headquarters of project in Ebute
Metta, the Senators also conducted an on the spot assessment of the earthwork
of the project across Lagos and assured all stakeholders of the Nigerian
Senate’s commitment to assisting the Executive arm in the actualization of
every developmental project within its purview.

Industries liable to receive Pioneer Status in Nigeria

Industries liable to receive Pioneer Status in Nigeria


The federal government on Monday, 7th August, 2017 , released
the full list of the 27 key industries and products included in the revised
list of ‘pioneer status’ incentives for prospective investors. This include –

1.     Mining and
processing of coal;
2.     Processing and
preservation of meat/poultry and production of meat/poultry products
3.     Manufacture of
starches and starch products;
4.     Processing of
cocoa;
5.     Manufacture of
animal feeds;
6.     Tanning and
dressing of Leather;
7.     Manufacture of
leather footwear, luggage and handbags;
8.     Manufacture of
household and personal hygiene paper products;
9.     Manufacture of
paints, vanishes and printing ink;
10.    Manufacture
of plastic products (builders’ plastic ware) and moulds;
11.  Manufacture
of batteries and accumulators;
12.   Manufacture
of steam generators;
13. Manufacture
of railway locomotives, wagons and rolling stock;
14.  Manufacture
of metal-forming machinery and machine tools;
15.  Manufacture
of machinery for metallurgy;
16.Manufacture
of machinery for food and beverage processing;
17. Manufacture
of machinery for textile, apparel and leather production;
18. Manufacture
of machinery for paper and paperboard production;
19.   Manufacture
of plastics and rubber machinery;
20.Waste
treatment, disposal and material recovery;
21. E-commerce
services;
22. Software
development and publishing;
23.    Motion
picture, video and television programme production, distribution, exhibition
and photography;
24.   Music
production, publishing and distribution;
25.   Real
estate investment vehicles under the Investments and Securities Act;
26.Mortgage
backed securities under the Investments and Securities Act; and
27.Business
process outsourcing.

Photo Credit – Here  
You can sue for a breach of promise to marry

You can sue for a breach of promise to marry


The Nigerian culture takes marriage really serious;
many young adults consider settling down as quite important and enter
relationships with the intention of spending time with this partner. Such relationships
could include casual flings, having an exclusive dating relationship or even
had led to an engagement with a promise to marry. However, sometimes these
relationships don’t work out and parties stop dating or being friends all
together.

What if a heart break could entitle you to financial
damages, will you act on it? So you met a great guy that swept you off your
feet, you had envisioned life with your man and maybe he had even proposed to
you before your friends and family. You gave him your world and you had both
agreed to get married but at the end of the day he ditched you for someone
else. The hurt sometimes can only be best imagined. However, did you know that
you may be entitled to damages for a breach of contract to marry?  
Nigerian law states that an agreement to
enter into a marriage should leave nobody in doubt as to the real intention of
the parties to enter into a marriage. A mere convivial or romantic relationship
without more is not enough for a court to found an agreement to marry. In
essence, there must have been a promise to marry. A promise to marry can be a
“betrothal”, an “engagement to be married” also termed “agreement to marry”. Such
agreement need not also be formal such as a written agreement as it may also be
oral.
For the purpose of proving a claim, two
elements are necessary to constitute a breach of agreement or promise of
marriage. First, the party jilted must prove to the satisfaction of the court
that there was in fact a promise of marriage under the Matrimonial Causes Act,
1990, or under Islamic Law or under Customary Law, on the part of the other
sex. Second, the party reneging has really, and as a matter of fact, failed or
refused to keep to the agreement of marriage.
In proving that there was a breach of
promise to marry, the claim must be corroborated by another witness or other
material evidence such as correspondences and communications, as the law specifically
states corroboration is required in actions of breach of promise of marriage. The
reliefs you can seek in court shall however be limited to damages as the court cannot
compel anyone to marry another. Extent of damages for such breach is however at
the discretion of the court.
Damages awarded by courts fall under the
following categories: general damages e.g. compensation for the loss of
consortium of the other party; injured feelings, wounded pride, etc ; special
damages affecting property e.g for money spent or financial loss sustained by
the plaintiff as a direct result of the defendant’s breach of the promise to
marry; recovery of the engagement ring and presents. An interesting thing to
note is that damages could also be claimed against a third party who induced
the breach.
It is important to note that not everyone
is bound by a breach of promise to marry. The other party may also have valid
reasons of defences for not carrying out the obligation. Such may include false
representation, or fraudulent concealment in material particulars, of the
pecuniary circumstances or previous life of the claimant. The bad character of
the claimant will also excuse the defendant from performance of the contract,
unless he or she was aware of the plaintiff’s character before making the
promise.
Physical or mental incapacity may give rise
to a right to terminate the engagement in limited circumstances. No disease or
infirmity short of absolute incapacity on the part of the defendant will avail
him or her, however, even if it is proved that the performance of marital
duties would endanger his or her life. The fact that the defendant honestly and
reasonably believed the plaintiff to be unfit to marry is no defence if the
plaintiff was in fact fit. Also, it is a defence to an action for breach of
promise that the plaintiff has released or discharged the defendant from
performance before any breach of the contract occurs. The release may be
express or implied.
What do you think, would you sue an ex for
a breach of promise to marry?
1.     www.lawreform.ie.
(2017). THE LAW RELATING TO BREACH OF PROMISE OF MARRIAGE. Available:
http://www.lawreform.ie/_fileupload/consultation%20papers/wpBreachofPromise.htm.
Last accessed 4th August, 2017.
2.     Ezeanah v. Atta
(2004) 7 NWLR (Pt. 873)468
3.     Lambe v. Jolayemi
(2002) 13 NWLR (Pt. 784) Pg. 356 Paras. E – G
4.     Orumor. (11th
October, 2016 ). The breach of promise to marry and its legal
consequences.
 Available:
https://guardian.ng/features/the-breach-of-promise-to-marry-and-its-legal-consequences/.
Last accessed 4th August, 2017 .
5.     The Honourable (Mr)
Justice Adebayo Manuwa v. National Judicial Council & Ors (2011)
LPELR-5015(CA)
Adedunmade
Onibokun
Photo Credit – www.patch.com 

3 things you can do when the police breach your legal rights | Adedunmade Onibokun

3 things you can do when the police breach your legal rights | Adedunmade Onibokun

That “Police is your friend” or “bail is
free’, a Nigerian will tell you is one of the biggest lies ever told in our
nation. If you doubt me, stop and ask any random person on the road or conduct
a poll. Daily, the news is filled with stories of police officers boldly collecting
bribes, demanding that bail be paid and even unlawfully extorting citizens. This
coming from a police that is employed to protect the citizenry and enforce our
laws is a big blow to democracy and life in Nigeria.

Sadly, the police hierarchy pays only lip
service to this problem that has bedeviled the police force for years. The
police condones such behavior from its officers else how can an officer have
the courage to stand in a police station and demand for bail, it is because he
or she knows that fellow colleagues in the station will not castigate the act
neither will the superiors punish it. Rather, other police officers will cover
up their law breaking colleague and even bear false witness against the victim.
But for how long will Nigerians tolerate these illegal and unscrupulous acts
from the Nigerian police. When will Nigerians be able to beat their chest and
credibly expect justice from the police. Our police officers have turned to the
job to a cartel of sorts and have succeeded in ridiculing the institution both
locally and internationally.
As active and responsible citizens, it is
important we raise our voice against the despicable acts. Due to fear, many Nigerians
have kept quiet and allowed these unruly behavior to go unchecked. Below are
steps a Nigerian or anyone visiting the country can take when faced with a
policeman who seeks to breach your legal rights or take advantage of you.
1.    
Make an official
complaint
The police in a bid
to clean up its ranks has established a procedure for reporting officers for
unethical acts or behaviours. The police has created the police complaints unit
dedicated to handling complaints against police officers. Via http://npf.gov.ng/complaint/, you can
register a complaint against any police officer. The Complaints unit can also
be reached via phone on 08057000001 or 08057000002. You may also send SMS via
08057000003 or via twitter and email on @policeNG_PCRRU and policepcrru@gmail.com respectively.
According to the
Police Complaints website on 4/8/2017, in the 1st quarter of 2017,
there have been over 498 total complaints received, out of which over 355 have
been closed or treated. The poor numbers of reports shows that not many
Nigerians are using the complaints unit to make complaints against the police. It
is recommended that more people do same.
2.    
Institute Legal
Proceedings against the police
The court is
described as the last hope for the common man to get justice. Hence it is
important for persons to approach the courts if their fundamental human rights
have been breached by members of the police force. The Nigerian Constitution
even provides in Section 35(6) that “ any person who is unlawfully arrested or
detained shall be entitled to compensation and public apology”. In instituting
legal action against the police it is important that the victim approaches a
good lawyer who will present the matter before the courts.
3.    
Use social media
The power of social
media can never be overemphasized. If you have the opportunity to record the
police officer in the act of extortion  or
committing an offence, post same on social media and crucify such officer on
the altar of public opinion.
Bad people prevail when good people do
nothing.
Adedunmade Onibokun Esq

Photo Credit – www.pulse.ng  

The Proposed NGO Regulation Bill  #NoNGOBillNG | Adedunmade Onibokun

The Proposed NGO Regulation Bill #NoNGOBillNG | Adedunmade Onibokun


“A dynamic and autonomous civil society, able to
operate freely, is one of the fundamental checks and balances necessary for
building a healthy society, and one of the key bridges between governments and
their people. It is therefore crucial that NGOs are able to function properly
in countries in transition, as well as in established democracies,”
Navi Pillay
High Commissioner
for Human Rights
United Nations

Over the past few months, there has been national
uproar over a very controversial Bill currently being debated by the National
Assembly, particularly the House of Representatives. Not only has this Bill
been denounced by Civil Society and other well-meaning Nigerians. The existence
of the Bill in itself is proof of the intention of federal lawmakers to silence
dissent and crush the activities of Civil Society that may seek to differ from Governmental
agenda.
Below are vital portions of the proposed
Bill which should get the attention of all Nigerians and the international
community with a view to forever silencing the Bill and raise our voices
against this Bill of the National Assembly which seeks to deprive Nigerians of
the right to hold government accountable.  
The Bill which is described as an act to
provide for the establishment of the Non-Governmental Organisations Regulatory
Commission for the supervision, co-ordination and monitoring of NGOs and Civil
Society Organisations in Nigeria is sponsored by Hon. Umar Buba Jubril from
Kogi State.
According to Section 7 of the proposed
Bill, the objectives of the commission includes –
a.     To enable the
transparency and accountability of the operations of Non-Governmental Organisations
and Civil Societies to accomplish their missions according to the law.
b.    To ensure the transparency
and accountability of the operations of NGOs and Civil Society.
c.      To supervise NGOs
and Civil Societies to ensure that they operate according to the law.
Furthermore, Section 8 of the proposed Bill
further provides for the functions of the Commission to include –
a.     
To facilitate and coordinate
the work of all national and international NGOs operating in Nigeria.
b.    
To maintain the
register of national  and international
NGOs operating in Nigeria, with the precise sectors, affiliations and locations
of their activities;
c.     
 To receive and discuss the annual reports of
the NGOs
d.    
 To advise the Government on the activities of
the NGOs and their role in development within Nigeria;
e.     
To conduct a
regular review of the register to determine the consistency with the reports
submitted by the NGOs and the council;
f.      
To provide policy guidelines
to the NGOs for harmonizing their activities to the national development plan
for Nigeria;
g.    
To receive, discuss
and approve  the regular reports of the
council and to advise on strategies for efficient planning and co-ordination of
the activities of the NGOs in Nigeria;
h.    
To receive, discuss
and approve the code of conduct prepared by the Council for self-regulation of
the NGOs and activities in Nigeria; and
i.      
Doing all such
things incidental to the foregoing functions which in the opinion of the Board
are calculated to facilitate the carrying on of the duties of the Commission
under this Act.
The
proposed Bill not only seeks to stifle dissent but it also proposes to
duplicate the functions being served by other existing legislations. Such legislation
includes the 1999 Constitution; Companies and Allied Matters Act (CAMA) of
2004; Companies Income Tax Act (CITA) of 2004; Value Added Tax Act of 1993;
FIRS Act; Personal Income Tax Act of 2011 etc. Furthermore, the Bill seeks to
create a commission whose establishment will lead to an increase in government
overhead, at a time when the government is currently spending N165 billion monthly on salaries of
federal civil servants.
The
Bill states in Section 11 that all NGOs shall be registered and shall among
other things state their sources of funding; location of their activities;
average annual budget; national and international affiliations and any other
information as may be prescribed.  However,
all NGOs are already registered by the Corporate Affairs Commission and granted
legal personalities under Part C of the Companies and Allied Matters Act (CAMA).
 The Bill also empowers the Commission to
exempt any NGOs it deems fit from registering. This will allow government to immediately
withdraw the registration of any NGO that dissents or objects to government actions
or policies in any way.
Furthermore,
any NGO which is not registered under the Commission, shall be unable to
operate in Nigeria, despite having attained legal status under the law. Registration
of which must be renewed every 24 (Twenty-Four) Months and can be denied if
seen to be against national interests or terms and conditions for certification
varied.The Commission shall also review and approve work permits for staffs of
NGOs.
The
proponents of the Bill argue that the requirement for CAC registration is not
sufficient for NGOs but this argument is similar to stating that all companies
in Nigeria must be registered by another government agency for the purposes of
monitoring. It is also claimed that the aim of the Bill is to ensure NGOS who
receive donations, do not abuse the funds collected in order not to soil the
image of the country. The Commission shall also issue a Code of Conduct to
regulate the funding and foreign affiliations of NGOs.
Clearly
the true intention of the Bill is to stifle the voice of Civil Society and it
should not see the light of day. Civil society is the conscience of a country
and must not silenced.   
Adedunmade
Onibokun